 A survey of 312 small and medium-sized enterprises (SMEs) in Phu Tho Province found a gap between businesses' awareness of the benefits of environmental, social, and governance (ESG) practices and their organizational capacity to implement them. The findings highlight the importance of internal resources, leadership commitment, and local policy support, as well as the need to tailor assistance to the specific conditions of different sectors.
From ESG awareness to business practice
ESG implementation capacity arises from the need to incorporate environmental, social, and governance requirements into business operations. To examine this issue, the study Identifying the Factors Influencing the Level of ESG Adoption among Small and Medium-Sized Enterprises in Phu Tho Province focuses on measuring ESG integration capability and examining its relationship with specific business practices.
The study was conducted by Nguyen Van Dung, MSc, and Associate Professor Nguyen Thien Dung. Nguyen Van Dung is a doctoral candidate in the Faculty of Economics and Management at Thuyloi University and a lecturer in the Faculty of Economics at Hanoi University of Natural Resources and Environment. Associate Professor Nguyen Thien Dung is affiliated with the Faculty of Economics and Management at Thuyloi University.
The authors define ESG integration capability as the ability to incorporate environmental, social, and governance requirements into long-term strategic directions, decision-making processes, operating procedures, and reporting systems. This construct is measured in the research model and reflects the organizational and governance dimensions of ESG implementation.
The level of ESG adoption is assessed separately through nine criteria covering the environmental, social, and governance pillars. These include waste management, energy use, emissions, and the use of sustainable materials; occupational safety, gender equality, and community-related issues; as well as transparency, business ethics, and risk management. The results are based on enterprise self-assessments rather than ESG ratings derived from an independent assessment framework.
The survey was conducted from March to June 2026, with respondents comprising business leaders and managers responsible for ESG or sustainability. Of the 380 questionnaires collected, the authors excluded 68 responses in which respondents had selected the same rating for all 37 questions, leaving 312 valid responses. The measurement instrument comprised 37 observed variables across eight constructs, using a five-point Likert scale. The data were analyzed using partial least squares structural equation modeling (PLS-SEM), together with tests comparing different groups of enterprises.
Six antecedents were examined: leadership awareness and commitment; internal resources; stakeholder pressure; local policy support; industry and market requirements; and perceived benefits of ESG adoption.
Internal resources stand out in ESG integration
Descriptive statistics show that perceived benefits received the highest score among the six antecedents, at 3.838, while internal resources received the lowest, at 3.344. ESG integration capability had a mean score of 3.443, compared with 3.805 for the level of ESG adoption. These values reflect assessments based on different measurement scales and should not be interpreted as enterprise ratings or performance classifications.
Among the conditions for implementation, management systems received a score of 3.247, while data and reporting systems scored 3.288. ESG training and the transparency and ease of implementation of regulations received scores of 3.327 and 3.353, respectively. These were among the lower-rated areas in the survey and were highlighted by the authors when formulating their recommendations.
The main model identified four antecedents that were positively and statistically significantly associated with ESG integration capability. Internal resources had the largest standardized path coefficient (β = 0.286), followed by leadership awareness and commitment (β = 0.207), local policy support (β = 0.180), and stakeholder pressure (β = 0.168).
Internal resources received the lowest descriptive score while showing the strongest association with ESG integration capability in the model. According to the authors, internal resources should be considered in terms of financial capacity, employees' knowledge and skills, data and reporting systems, and management systems. Support for ESG implementation should therefore place greater emphasis on enterprises' ability to organize their operations and manage information.
The leadership-related measurement scale examined the extent to which leaders understood ESG, incorporated their commitment into business strategies, communicated ESG priorities to employees, and maintained that commitment when facing difficulties. For local authorities, the assessed areas included the provision of information, incentives and support, training and capacity-building activities, and the transparency and ease of implementation of regulations.
The remaining two antecedents did not provide sufficient evidence of an association with ESG integration capability at the 5% significance level. Industry and market requirements had a p-value of 0.066, indicating marginal statistical significance at the 10% level, while perceived benefits had a p-value of 0.233. These findings do not necessarily mean that the two factors have no role in actual business practice.
In the main model, ESG integration capability was positively associated with the level of ESG adoption (β = 0.329; p < 0.001). The model explained 62.8% of the variance in ESG integration capability and 21.2% of the variance in the level of ESG adoption. The four antecedents identified above also had statistically significant indirect effects on ESG adoption through ESG integration capability.
However, an extended model produced different results regarding this mechanism. When direct paths from all six antecedents to the level of ESG adoption were added, the path coefficient for ESG integration capability was −0.102 and was no longer statistically significant (p = 0.125). The indirect effects through ESG integration capability were also no longer statistically significant. Under this model specification, perceived benefits had the strongest direct association with ESG adoption (β = 0.518; p < 0.001).
Thus, the mediating role of ESG integration capability is supported by the main model but is not robust to changes in model specification. The authors also identified limitations in the ability of the measurement scales to distinguish ESG integration capability from leadership awareness and commitment and internal resources. These issues should be considered when interpreting the findings. The available evidence is insufficient to establish ESG integration capability as the sole mechanism through which enabling conditions are translated into ESG practices.
Sectoral differences call for tailored support
Group comparison tests show clear differences in ESG adoption across sectors. Manufacturing enterprises had a mean score of 4.181, significantly higher than those in other sectors (3.564), construction (3.757), and commerce and services (3.844). The most pronounced differences were observed in the environmental pillar.
The group comparisons did not identify statistically significant differences in ESG adoption by legal form, workforce size, or revenue. Enterprises that had been operating for more than 10 years recorded a higher mean score, but differences associated with years of operation were not consistently confirmed across the statistical tests. The evidence of differences across sectors is therefore stronger than that of differences associated with enterprise development stage.
Based on the survey findings, the authors recommend providing support that addresses both organizational implementation capacity and awareness of ESG benefits. At the local level, proposed measures include self-assessment tools, simplified ESG reporting templates, and sector-specific training. The content of these interventions should be determined according to the management conditions, data capacity, and practical requirements of each enterprise group.
At the enterprise level, the study recommends incorporating ESG into business plans, assigning designated personnel to oversee implementation, and establishing a basic set of data on energy use, waste, and labor. Enterprises should also monitor measurable potential benefits, such as cost savings, opportunities to secure business orders, and access to finance. These are management recommendations rather than economic outcomes established by the survey.
Awareness of ESG benefits should be interpreted with caution. The strong association between perceived benefits and the level of ESG adoption in the extended model may be influenced by self-assessment, conceptual overlap between the constructs, or reverse causality: enterprises that have already adopted ESG practices may be more likely to recognize their benefits. Consequently, the available findings are insufficient to establish that increasing awareness of ESG benefits will directly increase the level of adoption.
The extent to which the findings can be generalized also depends on the composition of the sample. Enterprises in commerce and services accounted for 41% of respondents, while those with 10–50 employees represented 67%. Only seven enterprises operated in agriculture, forestry, and fisheries, equivalent to 2.2% of the sample. The findings should therefore be interpreted within the scope of the survey, with caution exercised when generalizing them to all enterprises in the province or specifically to the agricultural sector.
The study provides a basis for examining ESG implementation capacity in terms of enterprises' internal governance conditions. Data systems, operating procedures, clearly assigned responsibilities, and leadership commitment are specific areas that could be incorporated into support programs. Further testing with samples containing a more balanced sectoral composition, combined with verified information on actual business practices, would help clarify the relationships among ESG integration capability, perceived benefits, and the level of ESG adoption.
Source: Study entitled “Identifying the factors influencing the level of ESG adoption among small and medium-sized enterprises in Phu Tho province”, by Nguyen Van Dung and Nguyen Thien Dung, based on the manuscript provided.
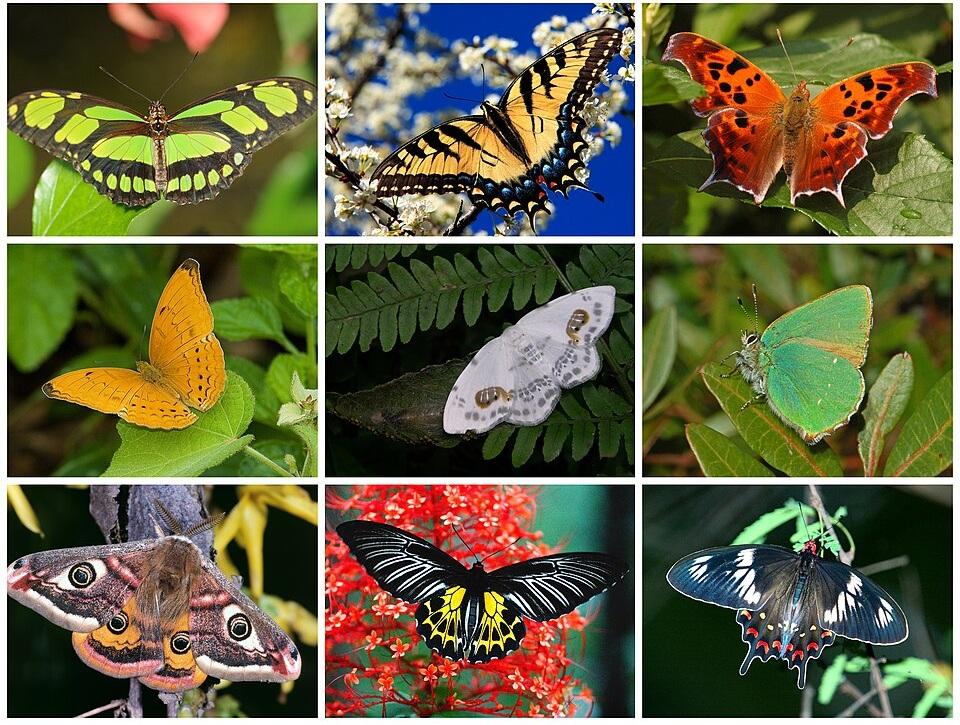
Surveys along 17 transects across six habitat types recorded 256 Lepidoptera species at Pu Huong Nature Reserve in Nghe An Province, including 66 species newly recorded for the study area. The findings expand the biodiversity record for an ecologically important forest landscape in western Nghe An and provide further insights into species distribution and the ecological roles of this insect group in forest ecosystems.
Viet Nam’s legal framework for greenhouse gas (GHG) management during 2020–2025 has evolved alongside the development of a measurement, reporting and verification (MRV) system, sector-specific technical regulations, and market-based economic instruments, including emission fees, the carbon market, and green credit. An analysis by Nguyen Thanh Giao, Nguyen Thi Lanh, Nguyen Van Linh, and Ha Thao Nguyen highlights the importance of linking emissions data, technical standards, and financial mechanisms to incorporate climate change mitigation objectives into production and investment decisions while supporting the development of low-carbon technological solutions integrated with the circular economy model.
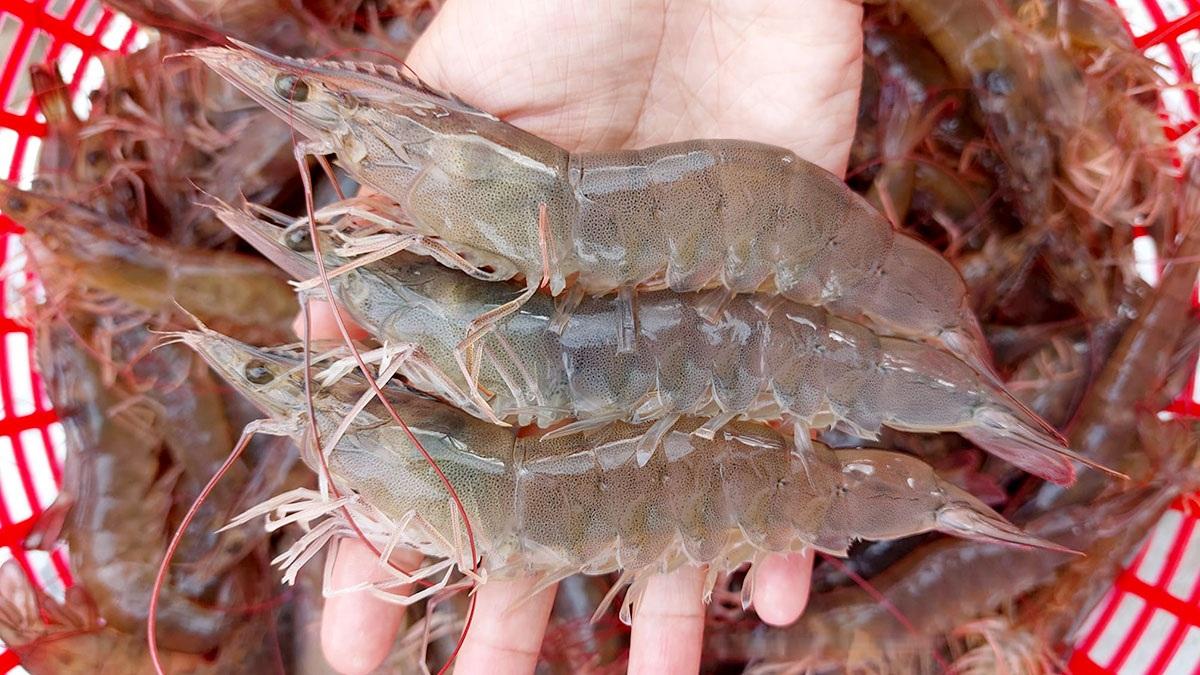
A survey of 90 whiteleg shrimp (Litopenaeus vannamei) farming households in the Mekong Delta found that probiotics are widely used in intensive and super-intensive production systems, whereas prebiotics and synbiotics remain less widely adopted. The findings provide practical evidence to inform the development of biological solutions better suited to production conditions, helping improve pond management and support more sustainable shrimp farming.
By 2025, Vietnamese agricultural products were being exported to more than 180 countries and territories, highlighting the need not only to expand market access but also to identify which markets should be consolidated, which offer further growth opportunities, and which warrant a more cautious approach. A study by Tran Cong Thang, Nguyen Anh Phong, and Vu Huy Phuc proposes a method for classifying agricultural export markets using a weighted set of criteria and tests the method on three major export commodities: rice, fruits and vegetables, and coffee. The findings provide a systematic reference for developing market strategies tailored to the characteristics of individual commodities.
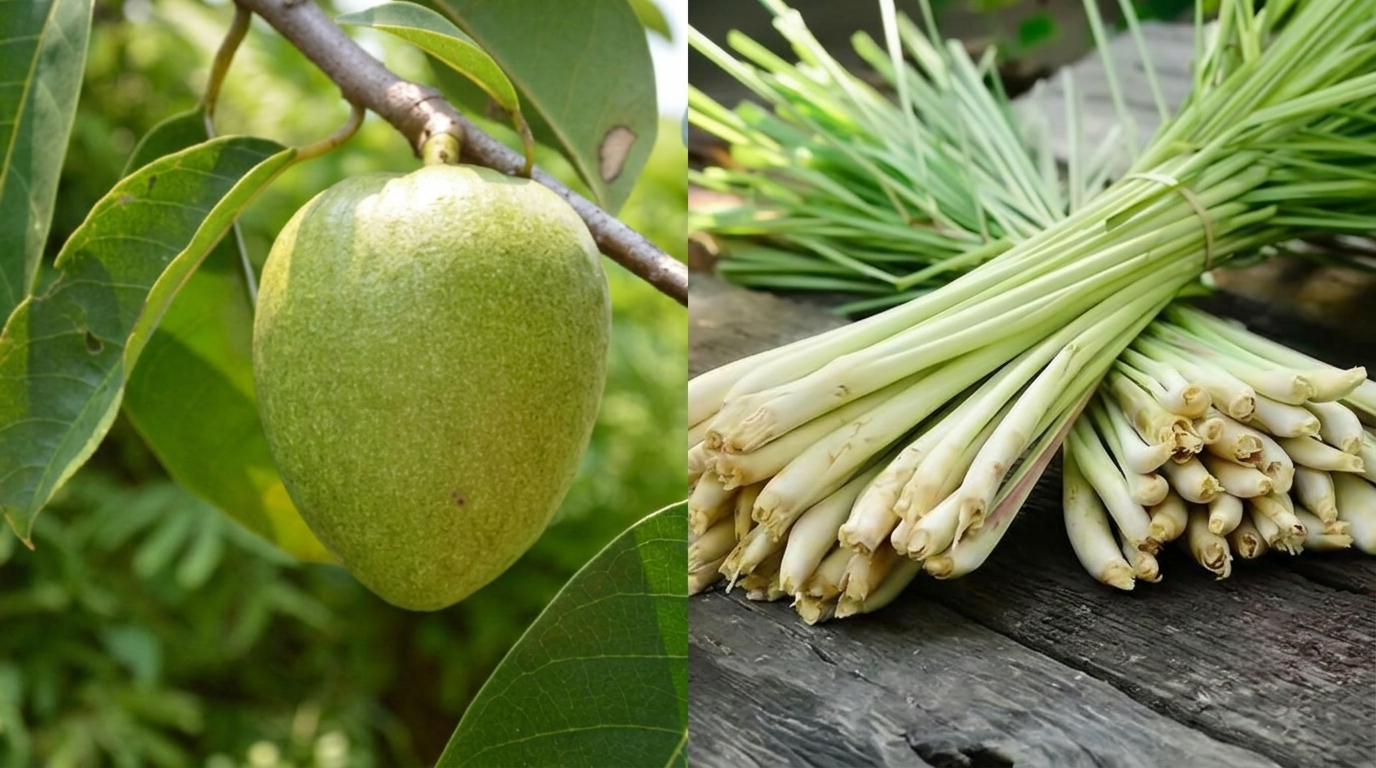
Research into plant-derived crop protection products is opening new avenues for sustainable agriculture. A study by Nguyen Van Phuoc, Ho Truong Huynh Thi Bach Phuong, Huynh Ba Di, and Cao Khoi Nghia of Kien Giang University found that nanoemulsions formulated from pond apple (Annona glabra) and lemongrass (Cymbopogon citratus) leaf extracts inhibited the fungal pathogen that causes rice blast and the bacterium responsible for bacterial leaf blight under laboratory conditions. These preliminary findings provide a scientific basis for further research into plant-derived formulations aimed at managing rice diseases while reducing reliance on synthetic chemical pesticides.