 Land-based revenues in Viet Nam more than tripled between 2015 and 2024, but their composition remains heavily dependent on land-use levies. Research by Phan Thi Thanh Huyen and colleagues highlights the importance of improving land data, strengthening information connectivity, and diversifying fiscal instruments to enhance land-based revenue mobilization.
Land-based revenues have grown, but remain concentrated
Land is both a resource for socioeconomic development and an important source of government revenue. As urbanization advances, infrastructure expands, and economic activity grows, land values may increase, underscoring the need for effective fiscal instruments to manage and mobilize land-based resources.
A study by Phan Thi Thanh Huyen, Ngo Thi Ha, Ta Ngoc Long, and Truong Quang Ngan draws on government budget data for 2015–2024 and 10 in-depth expert interviews to examine trends in land-based revenues in Vietnam, the factors influencing them, and the role of digital transformation in revenue administration.
According to state budget final-account data compiled by the authors, total land-based revenues increased from VND 85,982 billion in 2015 to VND 292,352 billion in 2024. This growth underscores the increasingly significant role of land resources in public finance.
However, an increase in revenue volume does not necessarily indicate a more stable revenue structure. Throughout the study period, land-use levies accounted for the largest share of total land-based revenues, ranging from 76.38% to 82.97%. By contrast, recurring revenue sources, particularly land-use taxes, continued to account for a relatively small proportion.
This composition indicates that government revenue remains heavily dependent on receipts associated with land allocation, the recognition of land-use rights, and changes in land-use purpose. Where land rent is paid as a lump sum for the entire lease term, receipts may also be concentrated in a single period rather than distributed over the duration of the lease.
The annual figures further illustrate this volatility. Total land-based revenues declined by 20.82% in 2023 compared with the previous year, before rebounding by 45.22% in 2024. The authors associate these fluctuations with the implementation of land allocation and leasing activities, the availability and utilization of land reserves, and conditions in the real estate market.
The significance of the findings therefore extends beyond identifying an upward revenue trend. The study highlights the need to improve the quality and stability of land-based revenues. A more balanced revenue structure should address two complementary objectives: mobilizing the economic value of land effectively and strengthening the capacity to sustain revenue over the long term.
Data quality and interoperability shape digital transformation
A notable contribution of the study is its examination of land-based revenue mobilization in the context of digital transformation. Rather than focusing solely on the volume of government revenue, the research considers how land data, land price information, and records of financial obligations can support revenue administration.
Expert interviews indicate that some localities have digitized cadastral records, developed land databases, and connected information systems to support the administration of financial obligations associated with land use. These initiatives can help public authorities retrieve land parcel information, determine land users' financial obligations, and monitor compliance with payment requirements.
The value of digital transformation lies in its potential to improve the quality of information underpinning administrative decisions. When information on land parcels, land users, land prices, and financial obligations is complete and regularly updated, public authorities have a stronger basis for determining amounts due, tracking changes, and monitoring the fulfillment of financial obligations.
However, the study also finds that the effectiveness of these efforts depends on data quality, the timeliness of updates, and the capacity of different systems to exchange information. Digitized records may not deliver their full potential if datasets remain inconsistent or cannot be effectively linked with tax records and real estate market information.
This finding has implications for the development of data-driven public administration. Digital transformation in land-based revenue management should not be assessed solely by the number of digitized records or public services delivered online. It should also be evaluated in terms of how effectively data can be used to determine financial obligations, monitor changes in land use, and improve transparency.
Nevertheless, the potential benefits of digital transformation must be distinguished from impacts that have been empirically measured. The study examines digital transformation primarily through its data and administrative dimensions; it does not quantify the specific effect of digitization on revenue outcomes. Integrated data can therefore be considered an important condition for improving administrative effectiveness, but not the only factor determining the capacity to mobilize land-based revenues.
Diversifying revenue sources and capturing land value increments
Based on their findings, the authors propose several policy directions to improve the composition and effectiveness of land-based revenue mobilization in Viet Nam.
First, reliance on one-off receipts should be gradually reduced, while greater attention should be given to recurring revenues associated with land use. This recommendation reflects the dominant contribution of land-use levies to total land-based revenues and the limited contribution of land-use taxes. Improving information on land parcels, land users, and assets attached to land, together with stronger links between land databases and tax data, could support more comprehensive identification and administration of financial obligations.
Another approach is to explore land value capture mechanisms. Land values may increase as a result of changes in land-use planning, infrastructure investment, or urban development. Under this approach, the government could consider appropriate fiscal instruments to capture part of the additional land value generated by these processes. Such mechanisms could provide supplementary resources for infrastructure development while helping balance the interests of the government and land users.
The study draws on international experience, including that of South Korea, where mechanisms such as land readjustment, development charges, and government-led urban development schemes have been used or examined. These experiences offer potential directions for policy research in Viet Nam. However, the selection and application of specific instruments must reflect the country's institutional conditions, land market characteristics, and legal framework.
To support the implementation of these policy directions, the authors emphasize the need to strengthen the data infrastructure for land-based revenue management. Priorities include improving the quality and consistency of cadastral data, updating land price information, strengthening links with tax data and real estate market information, and enhancing public authorities' capacity to use and analyze data. These conditions can support the determination of financial obligations, the monitoring of changes, and the oversight of revenues arising from land use and development.
The study also identifies limitations in its analytical scope. Nationally aggregated data do not fully capture differences across localities, while the specific effects of digital transformation on revenue outcomes have not been quantified. The authors recommend that future research combine government budget data with information on land, land prices, real estate transactions, and financial obligations. They also suggest developing indicators to assess the degree of digitization and the interoperability of information systems.
Overall, the study provides a useful basis for examining land-based fiscal policy and data governance together in the context of digital transformation. Its findings suggest that improving land-based revenue mobilization requires not only more effective fiscal instruments but also a reliable information system to support land valuation, the determination of financial obligations, and compliance monitoring. This approach is relevant to Vietnam's efforts to use land resources more effectively and strengthen the sustainability of public finance.
Sources: This article is based on the study “Assessing the current status of land-based revenue mobilization in Viet Nam in the context of digital transformation” by Phan Thi Thanh Huyen, Ngo Thi Ha, Ta Ngoc Long, Truong Quang Ngan, published in the Science Journal of Agriculture and Environment, Issue 2, July 2026.
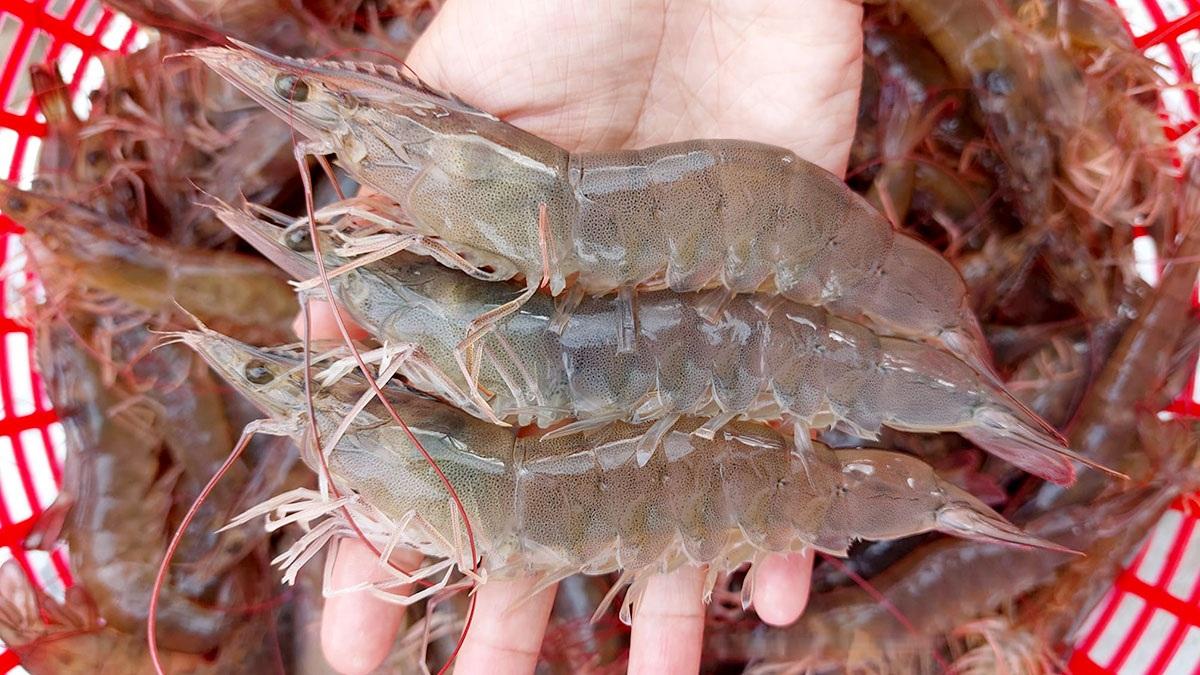
A survey of 90 whiteleg shrimp (Litopenaeus vannamei) farming households in the Mekong Delta found that probiotics are widely used in intensive and super-intensive production systems, whereas prebiotics and synbiotics remain less widely adopted. The findings provide practical evidence to inform the development of biological solutions better suited to production conditions, helping improve pond management and support more sustainable shrimp farming.
By 2025, Vietnamese agricultural products were being exported to more than 180 countries and territories, highlighting the need not only to expand market access but also to identify which markets should be consolidated, which offer further growth opportunities, and which warrant a more cautious approach. A study by Tran Cong Thang, Nguyen Anh Phong, and Vu Huy Phuc proposes a method for classifying agricultural export markets using a weighted set of criteria and tests the method on three major export commodities: rice, fruits and vegetables, and coffee. The findings provide a systematic reference for developing market strategies tailored to the characteristics of individual commodities.
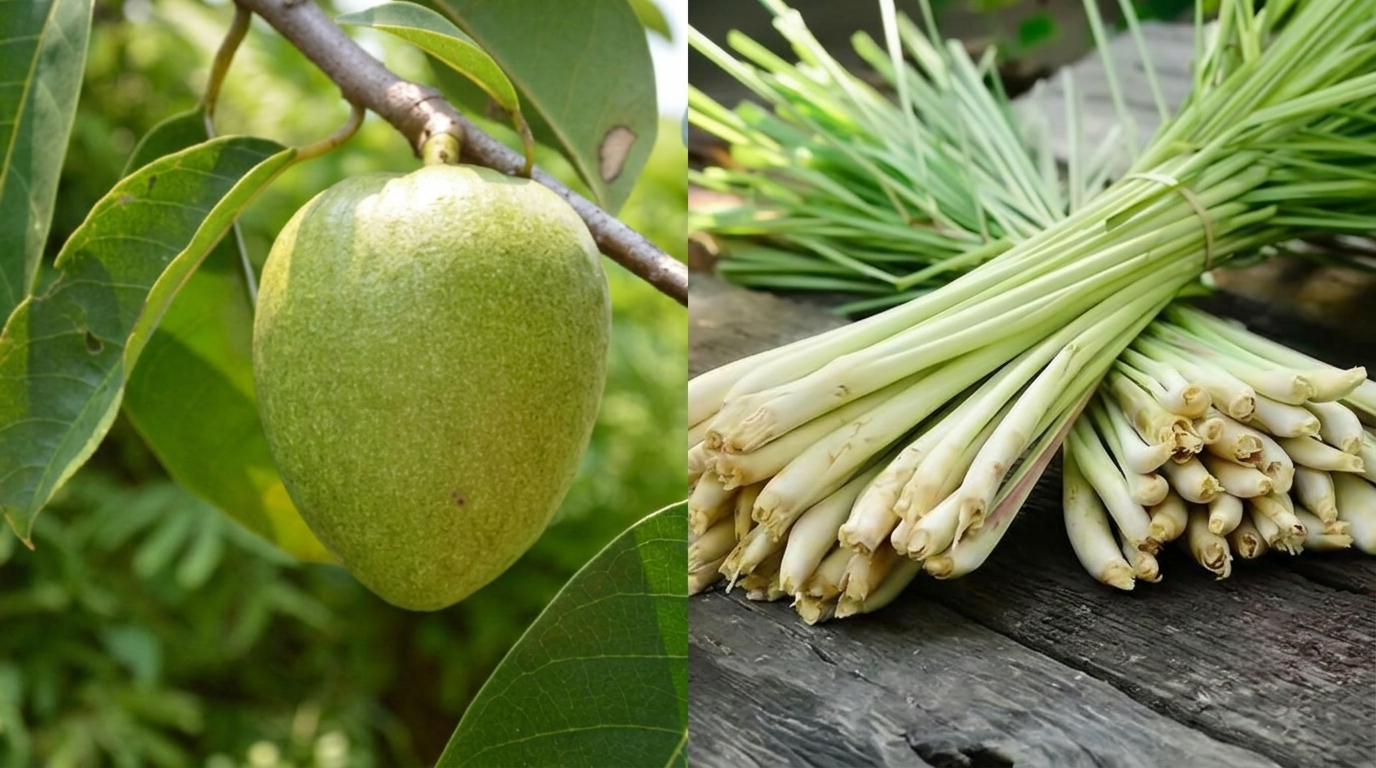
Research into plant-derived crop protection products is opening new avenues for sustainable agriculture. A study by Nguyen Van Phuoc, Ho Truong Huynh Thi Bach Phuong, Huynh Ba Di, and Cao Khoi Nghia of Kien Giang University found that nanoemulsions formulated from pond apple (Annona glabra) and lemongrass (Cymbopogon citratus) leaf extracts inhibited the fungal pathogen that causes rice blast and the bacterium responsible for bacterial leaf blight under laboratory conditions. These preliminary findings provide a scientific basis for further research into plant-derived formulations aimed at managing rice diseases while reducing reliance on synthetic chemical pesticides.
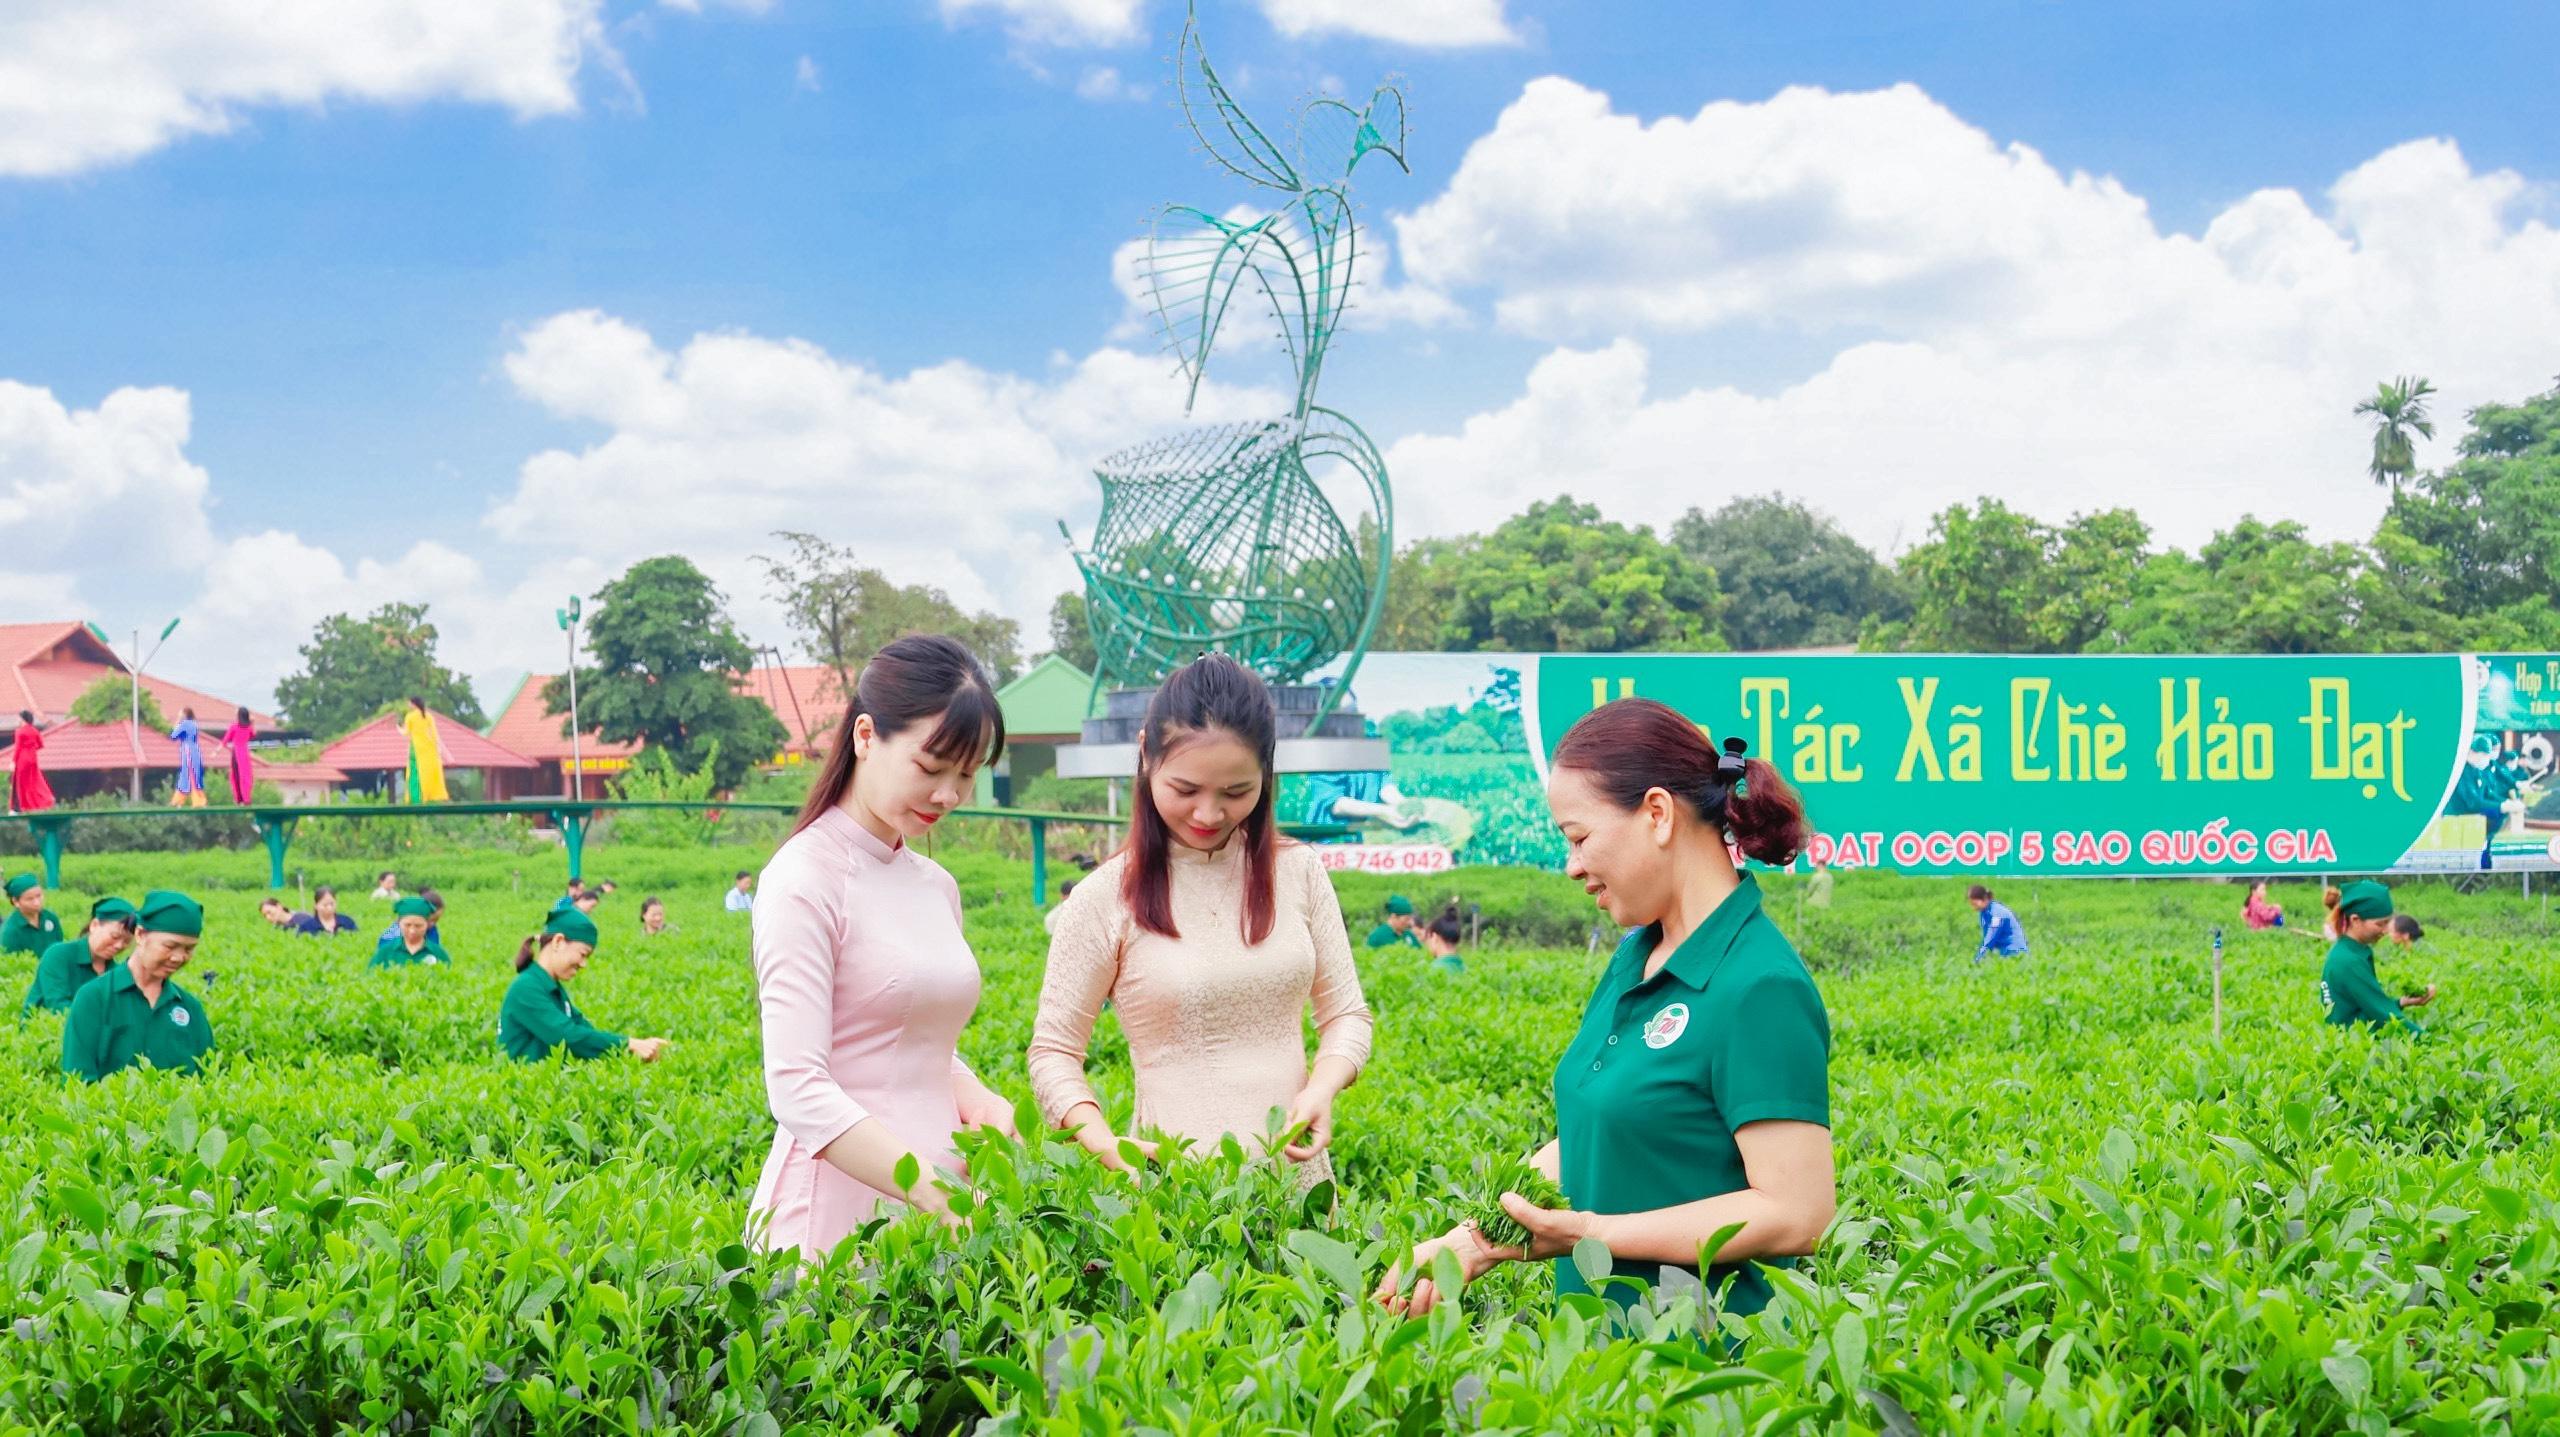
Effective implementation of the 2023 Law on Cooperatives requires not only dissemination of its provisions but also practical guidance and support mechanisms tailored to cooperatives’ operating conditions. A 2025 field survey conducted by Phung Giang Hai, Hoang Minh Huy, Vu Thi Thu Giang, and Nguyen Thi My across six localities identified challenges in applying six groups of new provisions and assessed support needs relating to legal compliance, governance, financial management, and operational arrangements. The findings provide an empirical basis for refining implementation guidance and developing support measures that better address the needs of agricultural cooperatives in Viet Nam.
A laboratory-scale study by Nguyen Thi Minh, Do Thi Thuy, and Le Minh Nguyet of Vietnam National University of Agriculture (VNUA) found that combining selected bacterial strains with microalgae improved domestic wastewater treatment efficiency. After 14 days, the combined system achieved a chemical oxygen demand (COD) removal efficiency of 96.67%, while substantially reducing organic pollutants, nutrients, and microbial indicators of contamination.